Can you finance used equipment? With used equipment financing, the answer is yes, potentially—but the machine’s condition and ownership history matter alongside your business finances.
Last updated: September 2026
Why This Matters for Business Owners
A used machine can reduce your purchase outlay compared with a new equivalent, but a lower asking price does not establish value. Deferred maintenance, missing accessories, or unavailable replacement parts can turn an affordable purchase into an expensive interruption.
Separate the financing decision from the buying decision. A provider evaluates whether a transaction fits its financing criteria. You still need to establish whether the equipment can perform the work you expect, in your facility, without exhausting your repair budget.
How This Financing Helps in Practice
Imagine you run a print shop and find a used finishing machine that could bring outsourced work in-house. Financing may help you acquire it while preserving cash for supplies and payroll. Explore Equipment Financing with the specific asset in mind, rather than treating every used machine as interchangeable.
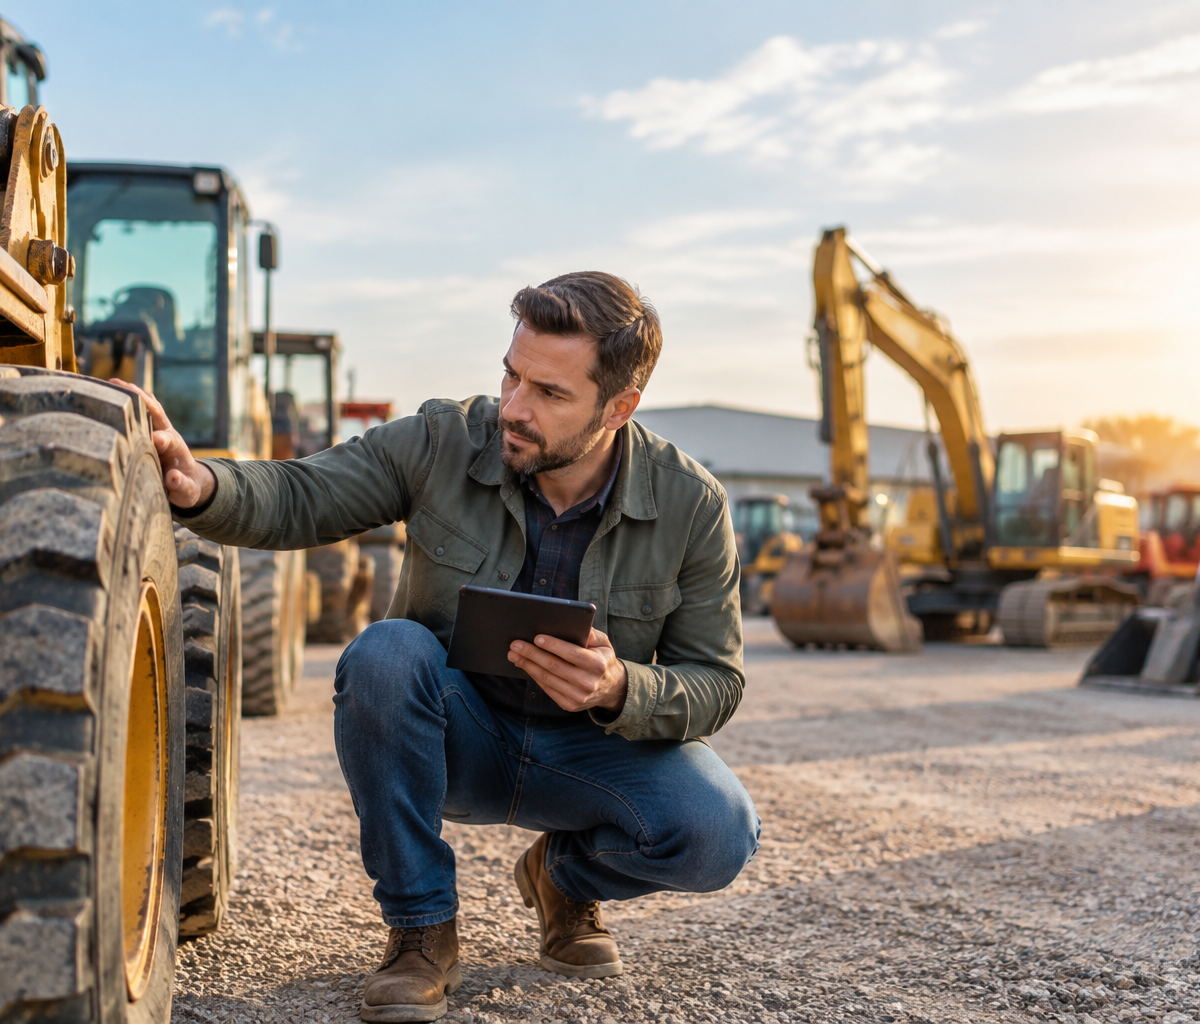
The purchase is more defensible when you have recurring work, an inspection supports the machine’s condition, and replacement parts remain available. Be more cautious if the benefit depends on unconfirmed orders or the seller will not allow an inspection.
Check practical compatibility, too: electrical requirements, floor space, operator training, software access, and removal from the seller’s premises can affect whether the equipment is usable at all.
Eligibility and Requirements
There is no universal used-equipment age limit or seller rule that applies to every provider. Depending on the financing arrangement, participating funding providers may consider:
- Business cash flow: Revenue, existing debt payments, and room for another obligation.
- Business and owner information: Operating history, ownership details, and credit information.
- Asset suitability: Make, model, serial number, condition, value, and expected remaining service life.
- Purchase structure: Seller identity, purchase documentation, upfront contribution, and collateral arrangements.
Participating funding providers may review credit and disclose their inquiry process before authorization. An initial eligibility review is not approval of you or the machine.
Ask specifically about private sellers, auctions, or refurbished equipment if relevant. Do not assume a provider accepts your transaction simply because it finances equipment generally.
Documents and the Process
Prepare a purchase file alongside your business records. Depending on the provider and transaction, requested documents may include:
- Seller quote or purchase agreement identifying the equipment and included accessories.
- Photos, serial numbers, maintenance records, and an independent inspection report.
- Ownership records and information about existing liens or required releases.
- Delivery, installation, and repair estimates.
- Business bank statements, financial statements, and existing debt details.
- Business identity and ownership information, including your EIN and requested owner identification, such as an SSN.
Start by confirming that the provider considers your equipment and seller type. Next, submit the requested records and resolve questions about condition, ownership, and costs. Review the written financing terms before authorizing the transaction or accepting payment obligations.
Clarify who pays the seller, when ownership transfers, and what happens if the equipment fails inspection. The overview of how the funding process works can help you distinguish a referral from a provider’s decision.
If a private-sale agreement or inspection condition is unclear, talk to a funding advisor about what to clarify with a participating funding provider before committing.
Free weekly newsletter
Get funding insights in your inbox
Weekly tactics, rate updates, and underwriting tips for U.S. and Canadian business owners. No spam — unsubscribe anytime.
Costs and Repayment
Ask for the amount financed, upfront cash required, payment schedule, total scheduled repayment, fees, and early-payoff terms. Confirm whether delivery, installation, taxes, or repairs can be included; do not assume every purchase-related cost is financeable.
The Federal Reserve’s small-business reports cover financing experiences and challenges, including borrowing costs (Fed Small Business Credit Survey). That context does not price your transaction: use the actual written offer to assess affordability.
Match repayment to conservative expectations for the machine’s usable life. If it stops working, your contract may still require payments. Keep maintenance and downtime reserves separate from the amount available for scheduled repayment.
Hypothetical example — illustrative assumptions only
Assume a used finishing machine costs $18,000, with $2,000 for delivery and installation. Assume no additional taxes or fees in this simplified example.
- Total acquisition cost: $18,000 + $2,000 = $20,000.
- Upfront contribution: $4,000.
- Amount financed: $20,000 − $4,000 = $16,000.
- Assumed repayment: 12 monthly payments of $1,500 = $18,000.
- Financing cost: $18,000 − $16,000 = $2,000.
- Total acquisition and financing outlay: $4,000 + $18,000 = $22,000.
These are invented arithmetic assumptions, not provider pricing or an available offer. A separate $3,000 maintenance reserve would increase the cash you plan for to $25,000, but that reserve is not an expense unless spent. The purchase needs to work financially without relying on that reserve to make scheduled payments.
Benefits and Tradeoffs
Advantages
- Spread acquisition payments while retaining cash for operating needs.
- Acquire a suitable used machine rather than paying for new features you do not need.
- Bring an established outsourced task in-house when the savings justify ownership costs.
Drawbacks and Risks
- Wear or limited parts availability can leave you paying for idle equipment.
- A secured agreement can put pledged equipment at risk if you default.
- Inspection, transport, and immediate repairs can consume cash outside the financed amount.
- Unclear ownership or unresolved liens can complicate the purchase.
Alternatives
Renting may fit temporary demand or let you test equipment before buying. Leasing may suit a different ownership preference, but review maintenance duties, return conditions, and any purchase option rather than assuming it costs less.
Cash purchasing avoids a financing obligation but reduces liquidity. Delaying the purchase while continuing to outsource may be safer when demand is uncertain.
SBA-backed lending is another route to investigate: SBA loan programs include financing uses involving machinery and equipment (SBA loan programs). That does not establish eligibility for your particular used asset; discuss the proposed purchase with a participating funding provider.
Expert Insight
The useful question is not simply whether someone will finance the machine, but whether it remains a sensible purchase after inspection and full costing. Keep the inspection decision independent from the financing offer. If the purchase works only when nothing breaks, revisit the budget before accepting repayment obligations.
Next Steps
Collect the seller’s quote, equipment details, inspection findings, and installed-cost estimate. Compare the proposed payment with cash flow after existing obligations and a maintenance allowance.
When the purchase file is ready, you can apply for business funding through Simply Approved Business Loans’ marketing and referral service. Participating funding providers determine eligibility, terms, and funding; submitting a request is not an approval.