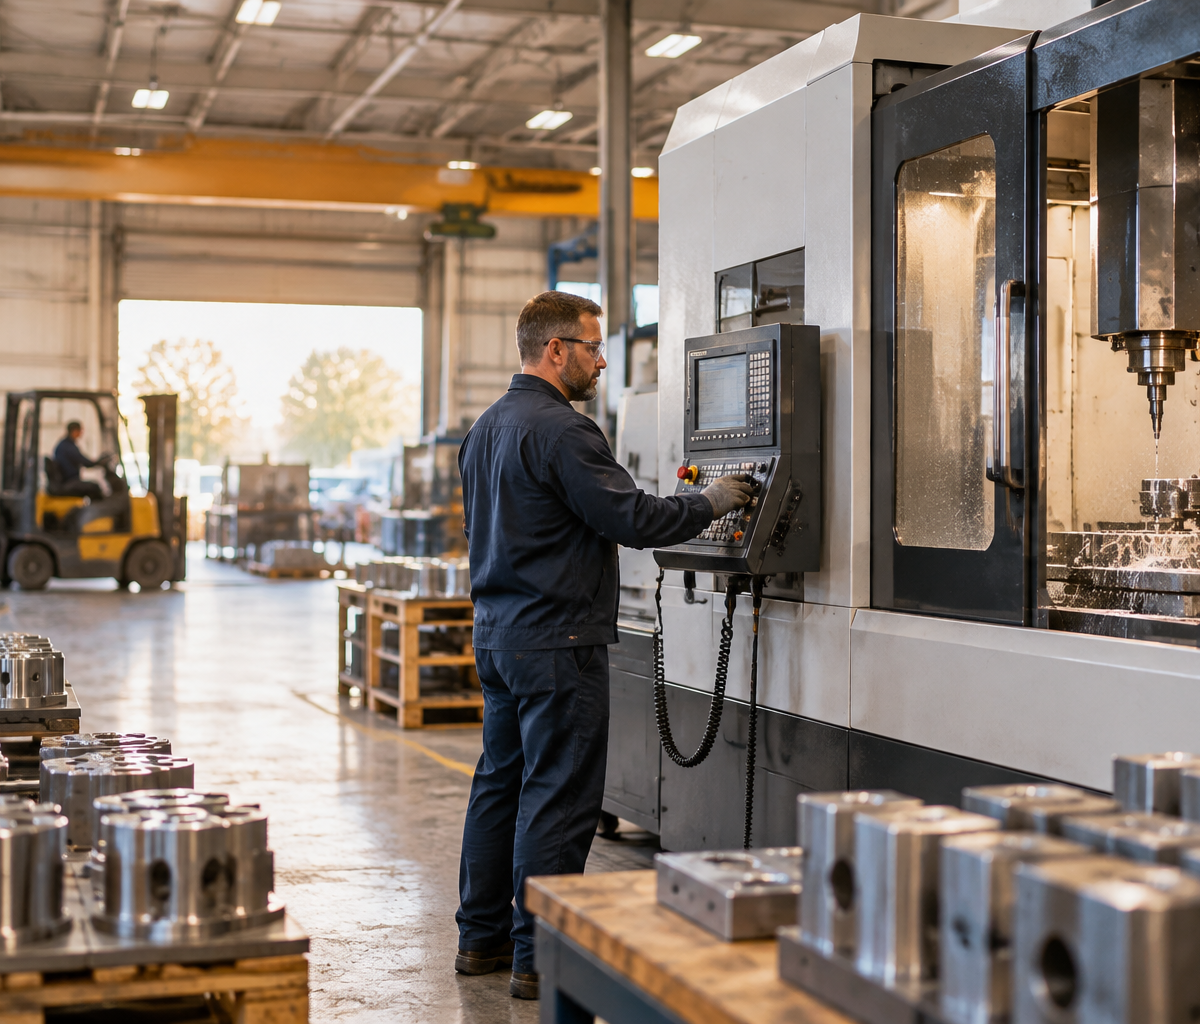
If you're considering manufacturing equipment financing in Louisiana, start with the cost of getting machinery into productive service—not just buying it. Your financing plan should connect the equipment purchase to installation, reliable output, and cash available for repayment.
Last updated: October 2026
Louisiana Manufacturing: Connect the Machine to Its Work
For a Louisiana shop serving energy, chemical processing, food production, or industrial maintenance, the useful question is specific: what work will this machine allow you to complete? A fabrication shop may need cutting capacity, while a food processor may need packaging equipment that keeps pace with upstream production.
Tie the purchase to your own operating conditions. Customer concentration, maintenance shutdowns, material availability, and specialized labor can affect whether added capacity becomes collected revenue. Do not treat a larger machine as proof of stronger demand.
Location alone does not establish financing eligibility. Participating funding providers assess the business, equipment, repayment capacity, and their own requirements. The Louisiana business funding page provides a starting point for the referral process; it is not a separate approval standard.
Define the Production Project Before Choosing Financing
An equipment purchase and a production-line project are not always the same financing problem. A replacement machine may fit an existing footprint and workflow. A new line can depend on conveyors, controls, electrical work, tooling, and operator training before it produces saleable goods.
Separate your budget into:
- Equipment: machinery, attachments, controls, and required tooling.
- Deployment: freight, rigging, installation, testing, and training.
- Operating cushion: materials, payroll, maintenance, and cash needed while output stabilizes.
Ask which items a proposed agreement covers and which you must pay separately. Equipment Financing is relevant to the asset purchase, but do not assume an equipment agreement includes every deployment or operating expense.
For a line with linked machines, identify the slowest production step. Financing faster upstream equipment may accomplish little if inspection or packaging remains the constraint. The manufacturing business loans guide addresses broader funding needs when the project extends beyond machinery.
What Participating Funding Providers May Review
Requirements vary by provider, but prepare to explain both the asset and the business supporting repayment. An equipment quote establishes what you want to buy; it does not establish that the purchase is affordable.
Useful preparation materials include:
- Business registration details, EIN, and owner identification information, including SSN where requested through an authorized process.
- Recent business bank statements, financial statements, and tax records, as requested.
- Existing debt obligations and their payment schedules.
- A supplier quote identifying the machine, condition, accessories, and purchase terms.
- An installation plan showing dependencies and responsibility for each stage.
- Cash-flow projections with the assumptions separated from existing operating results.
Participating funding providers may review credit and disclose their inquiry process before authorization. Ask what information is required and how to submit sensitive records securely.
For used machinery, prepare service records, condition information, and details about replacement parts. Review these used-equipment asset checks before relying on a low purchase price.
If you are unsure whether the request should cover a standalone machine or a connected line, talk to a funding advisor through Simply Approved's referral service about presenting the project clearly.
Compare Equipment Financing With Other Purchase Routes
A purchase-financing agreement should be evaluated against the actual ownership and payment obligations in its documents. A lease deserves a separate review of permitted use, maintenance responsibilities, end-of-term options, and return conditions. Product labels alone do not tell you which route fits your operation.
SBA-backed loan programs can support eligible equipment purchases, subject to the applicable program and participating lender's requirements (SBA loan programs). This is an alternative to investigate, not a statement that Simply Approved offers a government program or that your project qualifies.
A cash purchase avoids a new financing payment but reduces liquidity available for materials, payroll, and repairs. Delaying or staging the purchase may preserve flexibility, provided the smaller initial project can operate independently. Compare routes using the same equipment scope so an apparently cheaper option does not simply omit essential work.
Free weekly newsletter
Get funding insights in your inbox
Weekly tactics, rate updates, and underwriting tips for U.S. and Canadian business owners. No spam — unsubscribe anytime.
Calculate Installed Cost and Repayment Exposure
Request a written breakdown of the financed amount, cash required upfront, payment frequency, total scheduled payments, fees, and any final payment or purchase obligation. Ask about collateral, personal guarantees, prepayment provisions, and default consequences. These terms vary by agreement; do not infer them from a verbal payment estimate.
Delivery and commissioning deserve their own budget. The guide to financing equipment delivery and installation costs explains why the supplier's machine price may leave essential expenses outside your plan.
The Federal Reserve's Small Business Credit Survey reports examine firms' financing experiences and financial challenges (Fed Small Business Credit Survey). For your purchase decision, use your own cash records rather than treating broader financing conditions as evidence that the machine will pay for itself.
Hypothetical example — illustrative assumptions only
Assume a machine costs $80,000, delivery and installation cost $12,000, and tooling and training cost $8,000. The complete project costs $100,000. If you also reserve $15,000 for operating needs, the total cash requirement becomes $115,000.
For this planning exercise only, assume financing covers the $80,000 machine price. You would still need $35,000 from other available funds. This assumption is not an offered amount or a statement about provider coverage.
Suppose the installed machine generates $6,000 in additional monthly customer collections while adding $3,500 in monthly operating costs. That leaves $2,500 before financing payments, taxes, reserves, and other obligations. If collections reach only $4,500 while those costs remain unchanged, the contribution falls to $1,000. These figures illustrate operating sensitivity, not a rate, payment quote, or profitability forecast.
Use that lower-output scenario to test a written financing offer. Also test whether existing business cash can cover payments if installation produces no immediate revenue.
Coordinate Supplier Commitments With Funding Conditions
Before paying a deposit, clarify when it becomes nonrefundable and what happens if delivery, installation, or financing does not proceed as expected. A supplier's production schedule and a funding provider's requirements are separate commitments.
Ask the participating funding provider when payments begin and what must happen before funds are released. Ask the supplier what constitutes delivery, installation completion, and acceptance. Obtain written answers rather than assuming these milestones occur together.
For a connected line, establish who handles integration problems between machines. Keep responsibility for acceptance testing clear, especially when different vendors supply controls, conveyors, and core equipment. Financing a delivered asset does not by itself resolve a production system that fails to work as intended.
Why This Matters for Business Owners
New machinery is often one of the largest commitments a manufacturer makes. If installation runs late or output ramps up slowly, payments can start before the equipment produces revenue. Planning the full installed cost and a realistic ramp-up period helps you avoid a cash squeeze and compare offers on the obligations you would actually carry.
Benefits and Tradeoffs
Advantages
- Spreading purchase costs may preserve cash for materials and payroll during commissioning.
- A defined equipment project makes it easier to compare the same machinery scope across written offers.
- Replacing a documented bottleneck can support existing orders without requiring a broader facility expansion.
Drawbacks and Risks
- Payments may be due before the machine generates dependable customer collections.
- Installation, tooling, and operating expenses may remain outside the financed amount.
- Equipment liens or personal guarantees, where required, create obligations beyond the production benefit you expect.
- Specialized machinery may be difficult to redeploy or sell if demand changes.
Expert Insight
Judge the purchase by collected cash from usable output, not by advertised machine speed. A sound equipment proposal shows what happens when installation slips, scrap rises, or customers pay later than expected. If repayment works only at full planned utilization, reconsider the purchase scope or the cash cushion before committing.
Next Steps
For the full picture of funding options for manufacturers, see our manufacturing business loans guide.
When you are ready, you can apply for business funding and a funding advisor will walk you through what happens next. Gather the supplier quote, an installed-cost budget, and financial records showing how you would cover payments during commissioning. Then apply for business funding through Simply Approved's referral service if you want to seek a match with participating funding providers.
Simply Approved Business Loans LLC is an independent marketing, matching, and referral service. It connects U.S. business owners with independent participating funding providers. It is NOT a bank, direct lender, underwriter, or government program, and it never approves, funds, sets rates, or guarantees outcomes.
Related guides
- Equipment Financing for Manufacturing Owners 2026